October 2026 Ocean Freight Market Overview
October 2026 is likely to be one of the most operationally complex months of the year for China-origin ocean freight. The market is entering the month with sharply higher Transpacific East Coast rates, softer pricing on Asia–Europe services, rising bunker costs and an extensive program of blank sailings around China’s Golden Week.
The main October trend is therefore not a uniform increase or decrease across every trade lane. Instead, importers should expect a divided market:
- China–U.S. East Coast rates may remain exceptionally high because of fuel costs, geopolitical risk and limited capacity.
- China–U.S. West Coast space may tighten around Golden Week, although pricing will depend on post-holiday demand.
- China–Northern Europe and Mediterranean rates may remain under pressure, but blank sailings could temporarily slow further declines.
- Australia, New Zealand and intra-Asia services may experience schedule gaps, equipment imbalances and delayed post-holiday departures.
- Higher marine fuel prices may produce new or revised bunker and emergency surcharges across multiple routes.
For shippers, October should be treated as a month of capacity management and schedule risk, rather than a month in which headline freight rates alone determine the best booking decision.
Market note: All rate figures in this article are market indicators available on September 17–18, 2026. They are not fixed BRF Logistics quotations. Actual rates depend on origin, destination, carrier, container type, commodity, cargo-ready date, free-time requirements and local charges.
Key October 2026 Market Signals
The Drewry World Container Index stood at approximately USD 4,500 per 40-foot container on September 17, up 1% week over week. However, the global average hides a major split between routes: Transpacific rates increased by 6%, while Asia–Europe and Mediterranean rates declined by 7%.
Drewry also reported 77 cancelled sailings out of 720 scheduled sailings across the main East–West trades from Week 39 through Week 43, covering September 21 to October 25. This represents an 11% cancellation rate. Of the announced blank sailings, 55% were on the eastbound Transpacific, 31% on Asia–Northern Europe and Mediterranean routes, and 14% on the Transatlantic.
This capacity withdrawal is important. Even when cargo demand softens after Golden Week, fewer departures can keep individual vessels full, reduce routing choices and increase the risk of cargo rollover.
China Golden Week Will Shape the First Half of October
China’s National Day Golden Week runs from October 1 to October 7, 2026. The Mid-Autumn Festival holiday falls shortly before it, from September 25 to 27, leaving only a narrow working window at the end of September.
Major Chinese seaports normally continue operating, but the wider export chain does not run at full capacity. Factories, trucking companies, warehouses, documentation teams and supporting services may close or work with fewer employees. This can cause:
- late factory handovers;
- limited pickup appointments;
- missed CY and CFS cutoffs;
- documentation delays;
- blank sailings and port omissions;
- rolled containers;
- equipment shortages at selected origins; and
- congestion when operations restart.
The most difficult recovery period may extend from October 8 to October 16, when factories resume production and logistics providers process accumulated cargo. Importers should not assume that all services will return to normal immediately after October 7.
China to USA: East Coast Rates Enter October at a High Level
The Transpacific is the strongest major container market entering October. According to market data reported by Reuters, the China–U.S. East Coast spot rate reached approximately USD 10,948 per 40-foot container on September 17. Drewry’s Shanghai–New York benchmark increased by nearly 7% week over week to approximately USD 10,394 per 40-foot container.
The main supporting factors are:
- Pre-Golden Week cargo demand. Retailers and importers are moving cargo before factories close and export operations slow.
- Blank sailings. The Transpacific accounts for more than half of the announced East–West cancellations through late October.
- Higher bunker costs. Very-low-sulphur fuel oil rose sharply in September, increasing pressure for fuel-related surcharges.
- Middle East disruption. Security risks and changing vessel routings are affecting global fuel and network costs, including services that do not call directly in the Middle East.
- East Coast voyage exposure. Longer routes, Panama or Suez-related operational decisions, and inland delivery requirements can amplify total landed-cost volatility.
October Outlook for China–USA Shipping
Rates may remain firm during the first half of October, especially for U.S. East Coast destinations. A rapid fall should not be assumed while fuel costs remain elevated and carriers continue removing capacity.
After mid-October, two scenarios are possible. If post-holiday demand weakens, carriers may offer selective reductions on underfilled sailings. If carriers respond with additional blank sailings, effective capacity may stay tight and rates could remain supported.
Importers planning shipments can review our 从中国发货至美国 service hub or request a current sailing and landed-cost comparison from China BRF Logistics.
China to Europe and Mediterranean: Softer Rates, but Not Necessarily Easier Shipping
Asia–Northern Europe and Mediterranean spot rates were moving downward in mid-September. This suggests that October base freight may remain more negotiable than on the Transpacific.
However, lower market averages do not guarantee space on the exact vessel or departure week an importer needs. Carriers have announced significant Golden Week capacity reductions on these trades. Port omissions, service changes and more cautious vessel deployment may temporarily stabilize pricing or create short-lived increases around constrained departures.
The return of some services to the Suez route could eventually release capacity and shorten transit times. Nevertheless, security conditions remain volatile. Routing decisions can change quickly, so importers should confirm whether a quotation and transit time are based on Suez or Cape of Good Hope routing.
October Outlook for China–Europe Shipping
The most likely pattern is soft underlying demand combined with temporary capacity-driven firmness. Shippers with flexible departure dates may find better pricing after the holiday, while time-sensitive cargo should be booked against a confirmed schedule rather than waiting only for a lower headline rate.
For routing options, see Shipping from China to Europe and confirm the current carrier route before booking.
China to Australia and New Zealand: Watch Sailing Gaps and Equipment Availability
China–Australia and China–New Zealand trades may not follow the same rate direction as the U.S. and Europe markets, but they remain exposed to Golden Week capacity adjustments. Exporters should watch for:
- reduced sailing frequency during and immediately after the holiday;
- container shortages at inland or secondary Chinese locations;
- transshipment delays;
- tighter allocations on popular direct services; and
- higher origin trucking costs before factory closures.
For cargo that must arrive before the year-end sales or construction season, schedule reliability may be more important than securing the lowest possible ocean freight rate. Importers can compare options through our 从中国发货到澳大利亚 and China-to-New Zealand services.
Intra-Asia Freight: Short Transit Does Not Eliminate October Risk
Drewry’s Intra-Asia Container Index increased 6% to approximately USD 1,402 per 40-foot container on September 17. The movement shows that shorter regional routes can also react quickly to changes in capacity, equipment positioning and holiday cargo flows.
Shipments from China to Southeast Asia may face concentrated demand before the holiday and uneven schedules after it. Cargo that connects through regional hubs may experience an additional delay if the first sailing is missed. Importers should confirm whether a service is direct or transshipment-based and allow enough time for the connection.
Fuel Costs and Surcharges Are a Major October Risk
The 20-port average price for very-low-sulphur bunker fuel reached approximately USD 901.50 per metric ton on September 17, compared with USD 543.50 on February 27, according to figures cited by Reuters.
Carriers normally recover higher vessel operating costs through bunker adjustment factors, emergency fuel surcharges or general rate increases. As a result, an October quotation may change even when the published base ocean freight rate appears stable.
Shippers should check whether a quote includes:
- bunker adjustment factor or fuel surcharge;
- peak season surcharge;
- emergency risk or war-risk surcharge;
- origin terminal and documentation charges;
- destination terminal charges;
- demurrage and detention free time; and
- inland pickup and final delivery.
Comparing only the base ocean rate can create a misleading picture of the actual landed cost.
October 2026 Rate Direction by Trade Lane
| Trade lane | Expected October direction | 主要风险 |
|---|---|---|
| 中国至美国东海岸 | Firm to volatile at a high level | Fuel costs, blank sailings and geopolitical disruption |
| 中国至美国西海岸 | Firm around Golden Week; mixed later | Capacity cuts and post-holiday demand uncertainty |
| China to Northern Europe | Soft underlying market with short periods of firmness | Blank sailings, port omissions and routing changes |
| 从中国到地中海 | Soft to mixed | Capacity management and Suez-related uncertainty |
| China to Australia/New Zealand | Route-specific and schedule-sensitive | Sailing gaps, equipment and transshipment delays |
| 亚洲内部 | Mixed to firm on constrained services | Equipment repositioning and holiday disruption |
These are directional expectations, not guaranteed rate movements. October pricing may change rapidly by port pair and carrier.
What Importers Should Do in October
1. Confirm Cargo Readiness Before Booking
A low rate has little value if the factory cannot deliver before cutoff. Confirm production completion, packaging, export documentation and pickup timing before selecting a sailing.
2. Compare at Least Two Sailing Options
Ask for the vessel name, ETD, estimated transit time, routing, transshipment port and free time. A slightly higher-priced direct service may reduce rollover and connection risks.
3. Allow a Post-Holiday Buffer
Cargo prepared during Golden Week may not enter the export process immediately on October 8. Build extra time into factory pickup, consolidation, customs declaration and vessel departure planning.
4. Protect Time-Sensitive LCL Cargo
LCL shipments require warehouse receiving, consolidation and documentation before container loading. Missing a CFS cutoff can add an entire sailing cycle. Deliver urgent LCL cargo early and verify the consolidation schedule.
5. Review the Total Landed Cost
Check ocean freight, origin charges, destination charges, duty, tax, customs clearance and delivery before approving a shipment. This is especially important for DDP and door-to-door cargo.
6. Monitor Surcharges Until Departure
With bunker prices and geopolitical conditions changing quickly, confirm the final applicable surcharges before the container is gated in.
BRF Logistics October Shipping Support
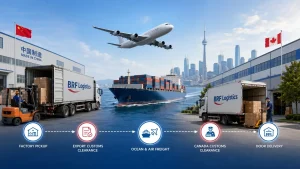
China BRF Logistics can coordinate the complete China-origin export process, including:
- supplier pickup and multi-supplier consolidation;
- warehouse receiving and container loading;
- export customs declaration;
- FCL and LCL booking;
- air freight for urgent cargo;
- destination customs coordination where available;
- DDU or DDP delivery on supported routes; and
- final-mile trucking and appointment delivery.
Because October conditions vary by route, the most useful quotation is based on a confirmed cargo-ready date, exact pickup address, destination postcode, commodity, weight, volume and container requirement.
October 2026 Ocean Freight Outlook: Final Assessment
The October ocean freight market will be defined by three forces: Golden Week disruption, carrier capacity control and elevated fuel costs.
China–U.S. East Coast pricing enters the month at an unusually high level. Asia–Europe pricing is softer, but blank sailings may prevent a smooth or continuous decline. Australia, New Zealand and intra-Asia shippers should focus on schedule gaps and container availability rather than relying on a global index.
For most importers, the best October strategy is to keep departure dates flexible, secure space against genuine cargo readiness, compare total landed costs and avoid depending on a single sailing.
Contact China BRF Logistics for an updated October 2026 freight quote and a route comparison based on your cargo details.
常见问题解答
Will ocean freight rates increase in October 2026?
Not on every route. China–U.S. East Coast rates may remain high, while China–Europe rates could stay softer. Blank sailings and fuel surcharges may still create temporary increases even on routes with weaker demand.
How will Golden Week affect October shipments?
Factories and supporting logistics providers may operate at reduced capacity from October 1 to 7. Blank sailings, missed cutoffs, delayed pickups and post-holiday backlogs may affect shipments into mid-October.
Should I book before or after Golden Week?
Cargo with strict delivery deadlines should be booked as early as possible. Flexible cargo may find more options later in October, but carriers can remove capacity if demand weakens, so lower rates are not guaranteed.
Why are China–U.S. East Coast rates so high?
The main factors are pre-holiday demand, carrier capacity reductions, higher bunker fuel costs and geopolitical disruption affecting vessel operations and surcharges.
Are October freight rates guaranteed once quoted?
Only within the validity and conditions shown on the quotation. Space, equipment, surcharges and local fees should be reconfirmed before booking and again before departure.